When the economy turned sour a number of years ago, many families turned to rental housing as a more economical alternative to what had become unaffordable mortgages. But with the housing market’s recovery, that trend had reversed. Home-buying’s advantages are looking better all the time.
On the national level, even as the rise in home prices has started to slow, rents have kept increasing. Combined with stable prices, today’s great low mortgage rates are also working in buyers’ favor, ensuring that monthly payments will be low.
Looking ahead, it’s likely that rental rates will rise faster than inflation. That has been true historically, and there’s little reason to think that trend will change.
Overall, it’s now 38 percent less expensive to buy than to rent a comparable home, according to national statistics. Even though economists expect some increase in interest rates as the Federal Reserve phases out its stimulus programs, that’s unlikely to tip the balance away from homeownership. Mortgage rates would have to rise to 10.6 percent before renting would be cheaper than buying. Loan rates haven’t been that high since 1989.
As the market stands now, I’m advising would-be homebuyers to lock in a mortgage payment now, before both interest rates and real estate prices rise again, as experts predict they will.
Whether to buy or rent is one of the biggest financial decisions anybody will make during their adult life, so it’s important to weigh all the pros and cons.
These are some of the clear advantages of buying over renting.
Mortgage interest and property taxes are both deductible on a family’s personal income tax return. Renters get no comparable tax break.
Homeowners enjoy pride of ownership, and the freedom to make their homes reflect their tastes, in ways renters can’t. You can paint, landscape, improve and update your house however you choose, without any restrictions imposed by a landlord. And those improvements belong to you, either to enjoy indefinitely or to improve your price if you sell.
Buying a home is a genuine investment. Since part of every mortgage payment goes toward the principal, it’s like putting money into a savings account, but with a much better return. Over the long term, home prices have appreciated 3 percent to 5 percent each year. So the longer you stay in your home, arguably the better the investment and the higher your return.
Of course, owners do have costs and obligations that renters don’t – at least not directly.
The homeowner must pay taxes and insurance, which typically come out of the monthly mortgage payment. (But those costs are built into rents, too. Just not tax-deductible!) In many neighborhoods, homeowners association dues are also required.
An owner is responsible for all maintenance. There’s no landlord to call when the plumbing backs up, the heat pump quits or the roof leaks.
On the other hand, everything a renter spends on housing is gone as soon as the next month’s rent comes due. There’s nothing to show for that money when the renter moves out. Compared to building equity in a home you own, rent looks like just throwing money away.
And then there’s the matter of moving out. Even with a lease, renters may be forced to move whether they want to or not. The landlord might sell a property, or move into it himself, or use it to house a relative. Or, for whatever reason, the owner might just decide not to rent to you anymore.
Also, unlike a mortgage payment, which is guaranteed by a long-term contract, rents can and do go up from year to year.
Homeownership remains the surest way for most families to build wealth and invest in their futures.
So while renting carries fewer obligations, it also offers far less security, either for your current living arrangements, or for your long-term financial health.
Michelle Clark is a broker with Intracoastal Realty, based at the Wrightsville Beach office. She is an Accredited Luxury Home Specialist, ALHS and also a Short Sales and Foreclosure Resource. Whether you are buying, selling, or investing, know that Michelle and her team will go the extra mile for you. To learn more about Michelle and Intracoastal, go to www.intracoastalrealty.com. You may contact Michelle at [email protected] or 910-367-9767. Like Michelle’s team on Facebook at www.facebook.com/MichelleClarkTeam.


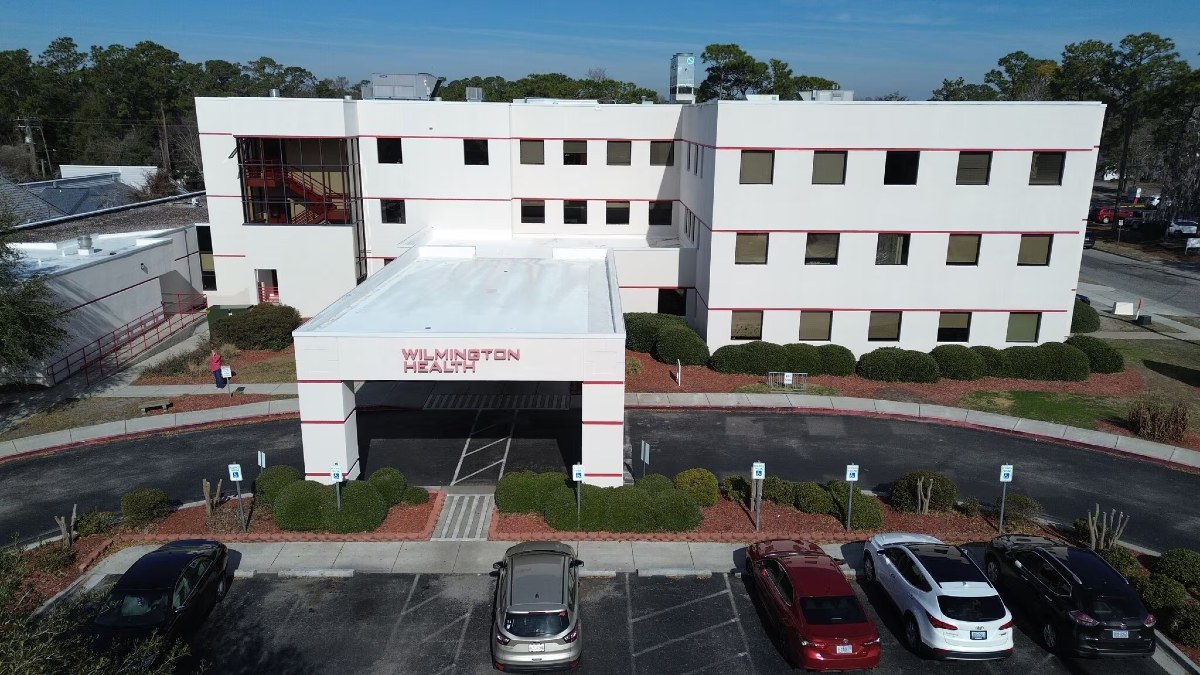
Wilmington Health Facility Sells For $9.4M
Cierra Noffke
-
Oct 26, 2026
|
Industry professionals say people seem much more willing these days to travel to the Wilmington area outside of the traditional summer vacat...
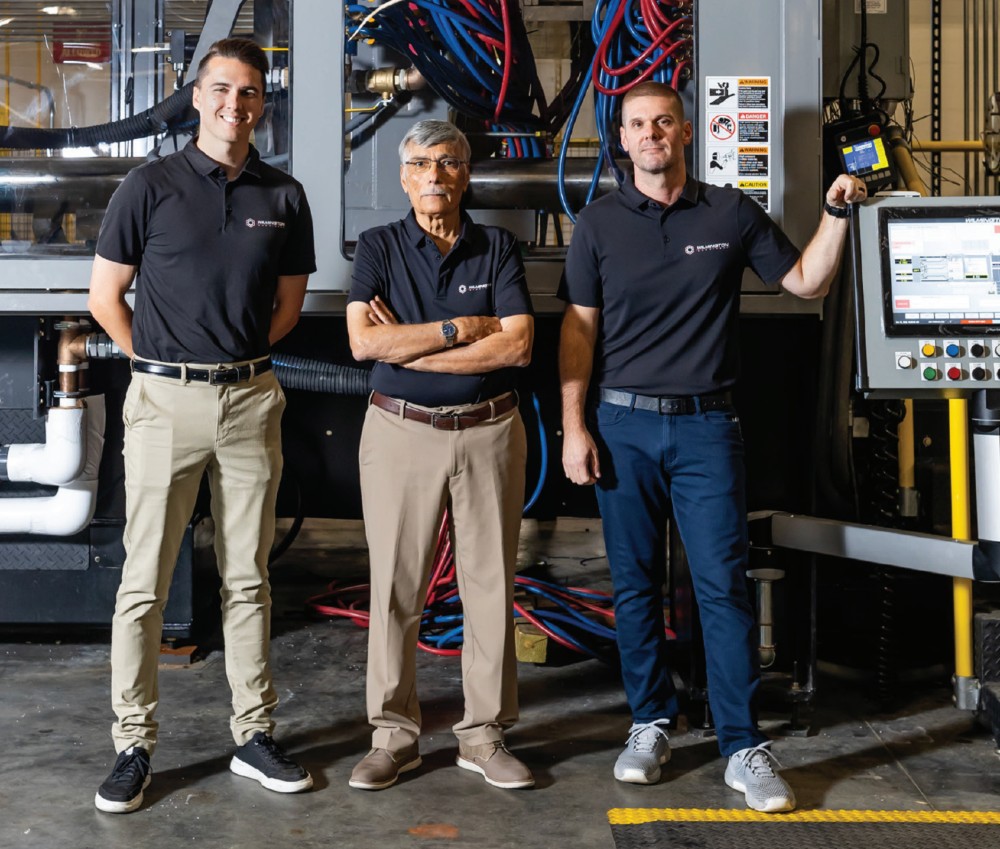
Now under the ownership of Yousry Sayed, the founder of Quality Chemical Laboratories, Wilmington Machinery is eyeing business growth....
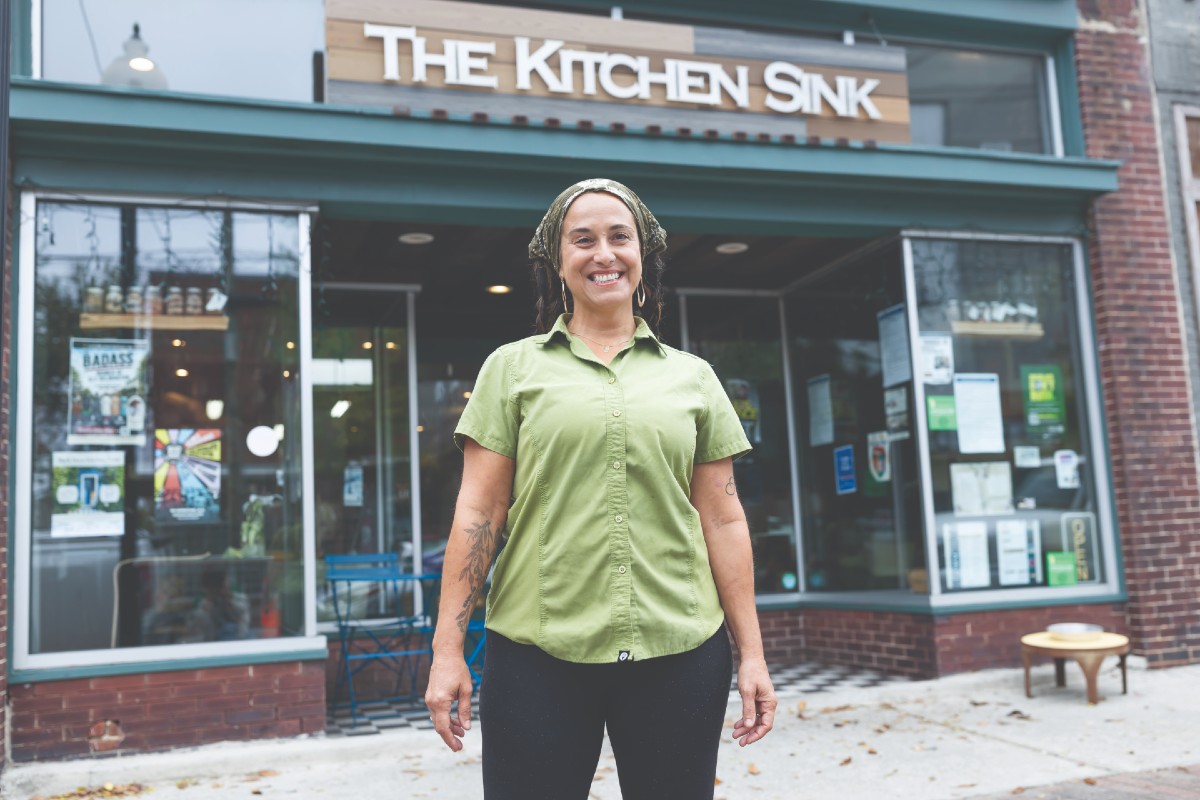
Mitchell is facing many of the same struggles as other restaurants. Despite the challenges, Mitchell said she won’t compromise on food quali...
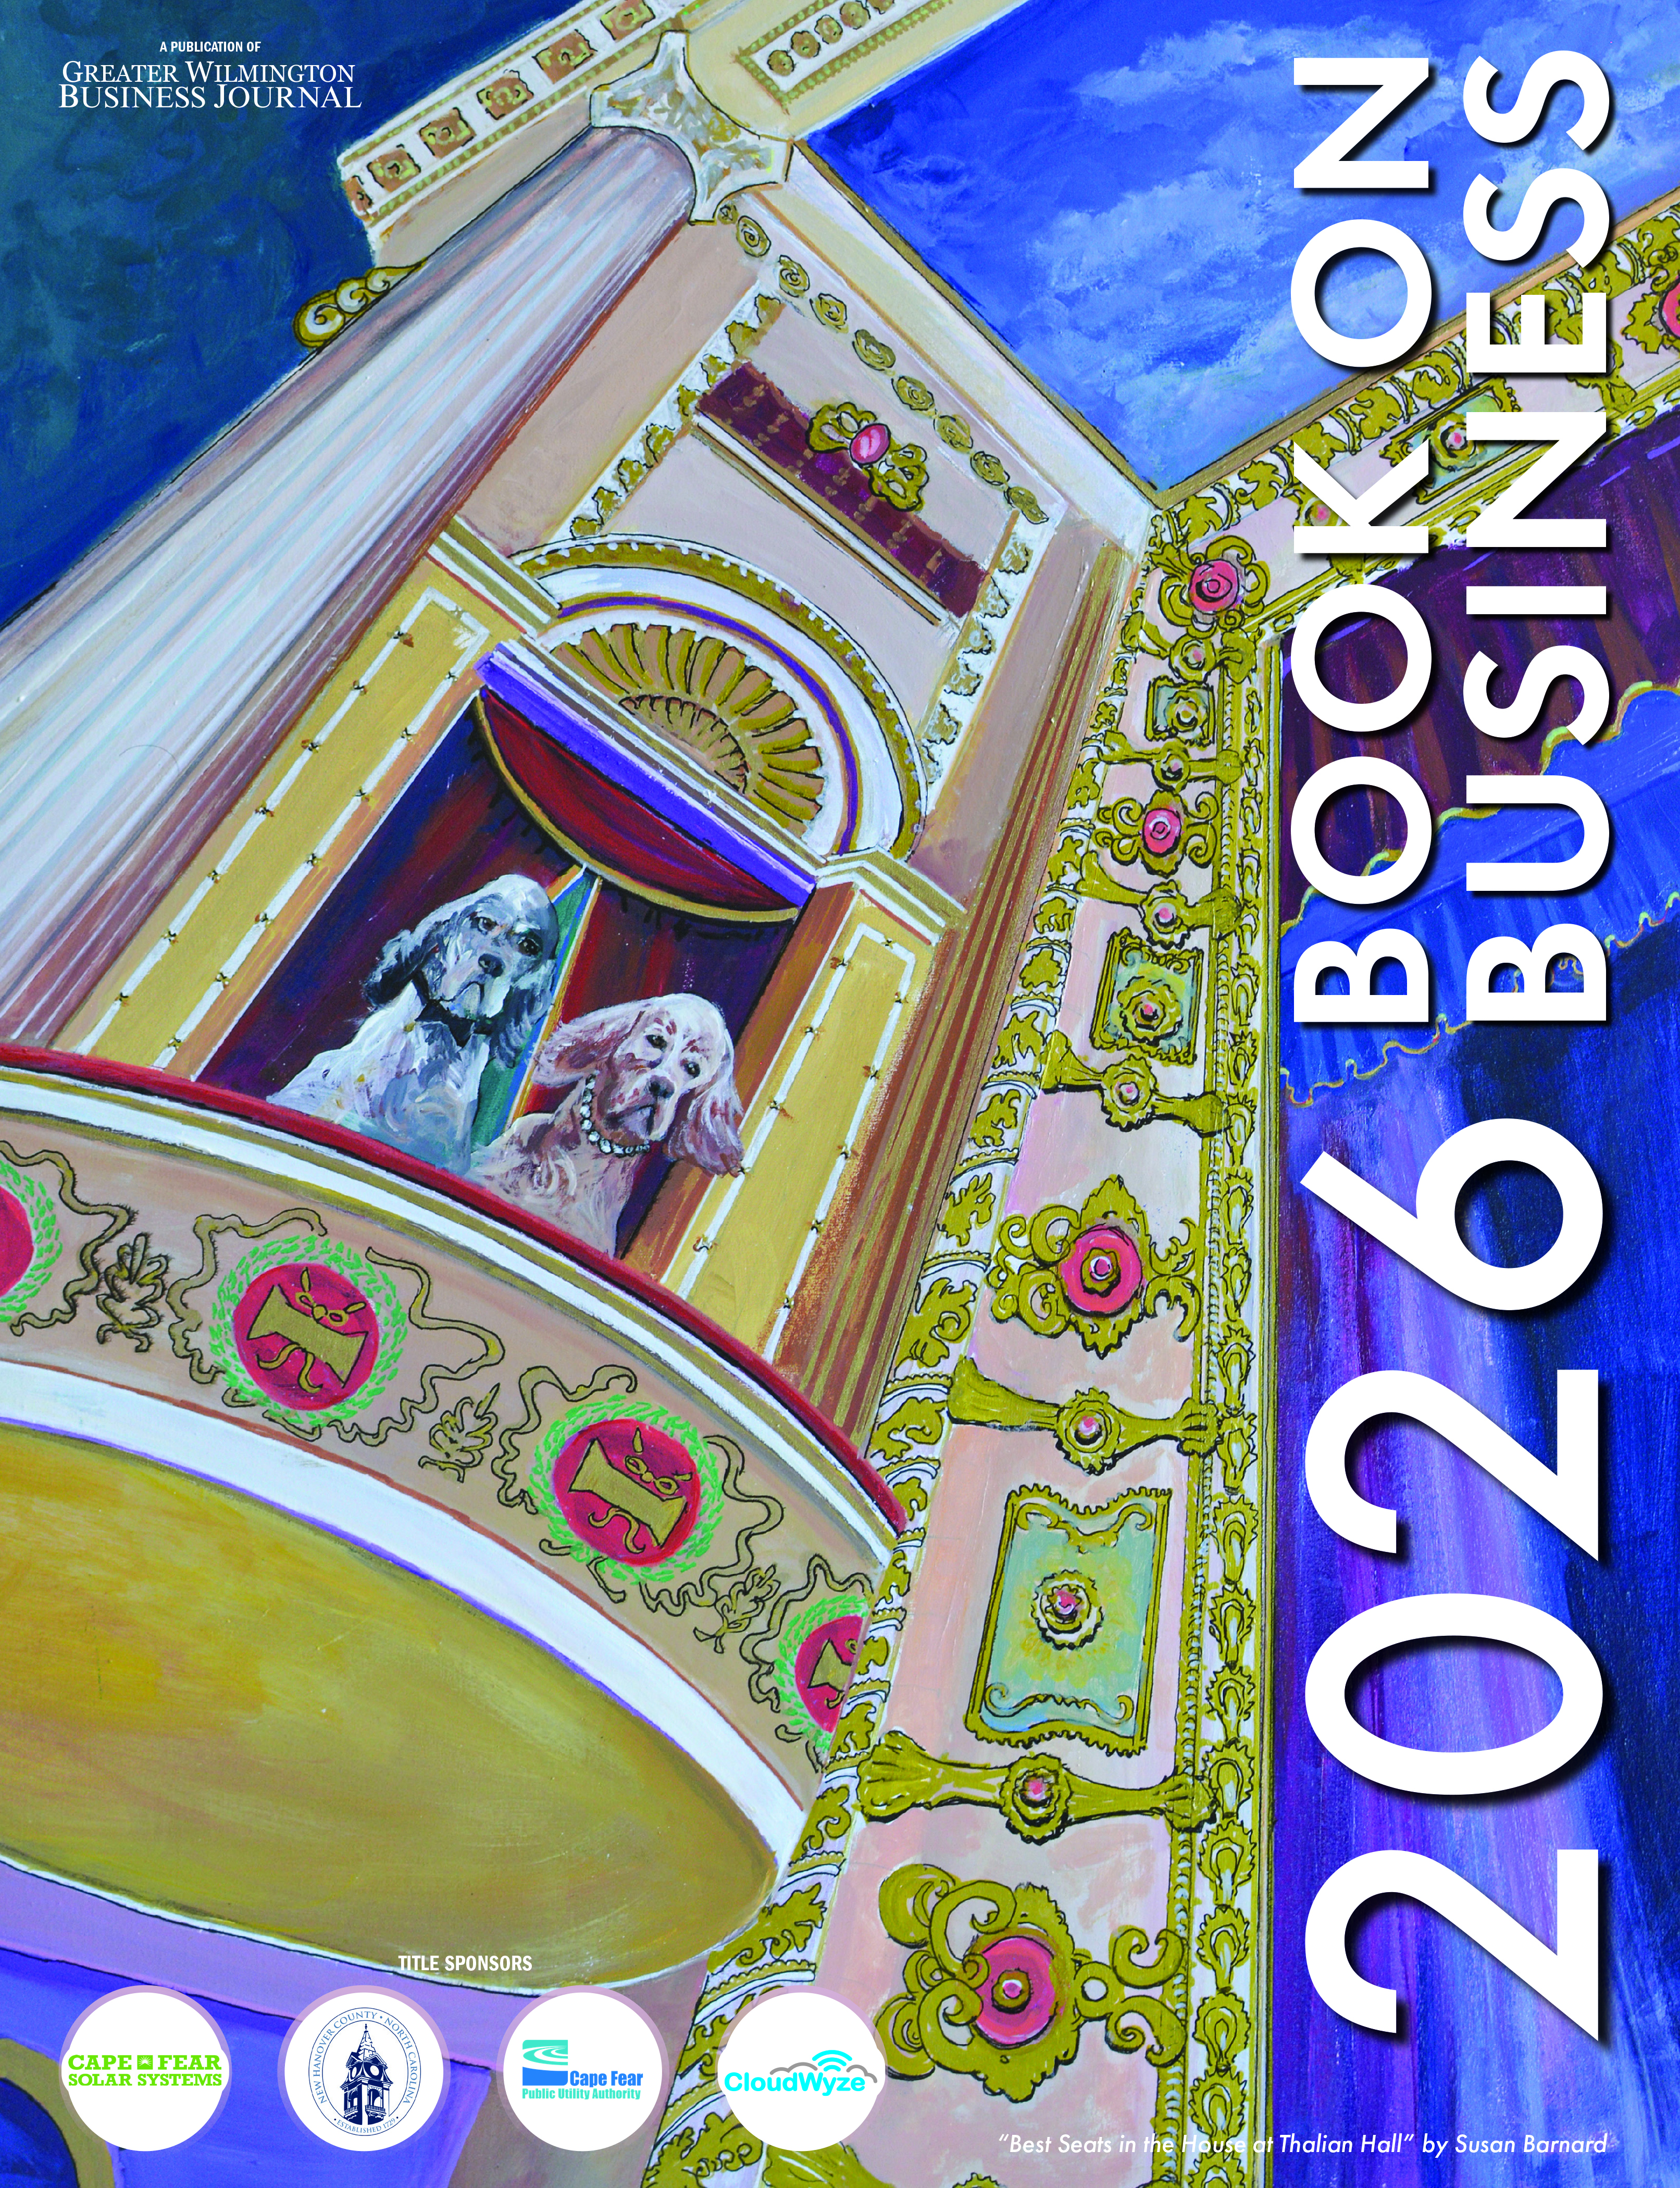
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.