It seems like we break rainfall records more often these days… or maybe that’s just my imagination.
With the 2018 hurricane season having just kicked off, it’s a good time for homeowners to check on the availability of flood insurance to protect your home. Flood insurance for moderately-priced homes in moderate risk areas is a good buy.
For as little as $380 a year, you can purchase $200,000 in building coverage and $60,000 in contents coverage. The average premium is about $700 a year, even though the federal government is phasing out coverage subsidies. I recommend buying it! It paid for itself hundreds of times over when my house flooded during Hurricane Floyd.
Many folks don’t have flood insurance. In my experience, this is because they don’t feel the need if the coverage is not required by a bank, which is often the case if the area does not often flood.
A recent news report confirmed this – a local homeowner did not buy flood insurance because he thought it was available only for homes in a "flood zone."
That is not so.
And since then, I have heard some folks say the opposite – they thought you could get flood insurance only if you are not in a flood zone. That is not so, either.
In my opinion, you need flood insurance, even if you don’t live in a high-risk area.
While floods are the number-one cause of disaster in the U.S., many folks think they are not at risk if their homes were never flooded. Wrong. The risk can change for the worse over time.
For example, increased development can replace nearby natural areas with impervious surfaces. In that event, heavy rains are no longer quickly absorbed into the ground. Instead, they quickly run over the hardened surface… and in the direction of a formerly “dry” home.
Combine that with rapid rainfall accumulation, poor drainage systems, or backed-up water mains and you can have a real problem on your hands. Small wonder that more than 20 percent of National Flood Insurance Program (NFIP) claims are not from high-risk areas.
Here are a few things you need to you know about flood insurance:


Ashworth Joins Mincey Bell Rhoades Law Firm
Staff Reports
-
Sep 15, 2026
|
|
Brunswick County Planning Board To Consider 450-home Development Plans
Cierra Noffke
-
Sep 14, 2026
|
|
Pipe And Valve Distributor Opens Wilmington Branch
Staff Reports
-
Sep 15, 2026
|
|
Wilmington-area Companies Named Finalists For NC Tech Awards
Cierra Noffke
-
Sep 15, 2026
|
|
Southport-Oak Island Chamber Announces Summer Awards
Staff Reports
-
Sep 15, 2026
|
|
The expanding footprints of Perennial Harbor and Blossom Bay are among the latest examples of growth in the Soda Pop District, which stretch...
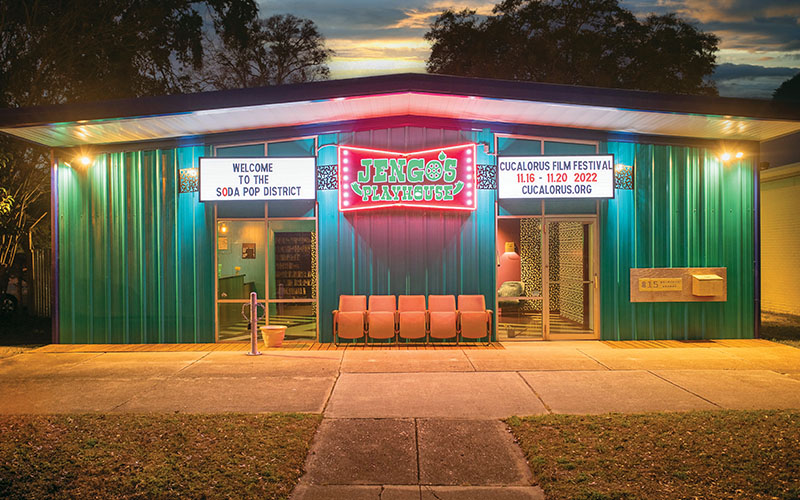
Dan Brawley, head of the Cucalorus Film Festival and founder of Jengo’s Playhouse, recently discussed the venue’s year-round efforts and thi...
John Thomason used the loan he received from the fund, which now provides up to $15,000 for high-demand workforce training, to help cover mo...
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.