This article discusses a few strategies for managing the tax implications of Required Minimum Distributions and minimizing one’s total lifetime tax paid.
For many Americans, 401(k)s, 403(b)s, IRAs, and other types of qualified plans are the primary way to save for retirement. These accounts are great wealth-building vehicles, allowing individuals to invest for the future and reduce their taxes along the way. Contributions often grow for years, even decades, with no tax implications for the investor. However, when a withdrawal occurs, the full amount becomes taxable, and Uncle Sam finally gets his due.
Understanding IRA Required Minimum Distribution
To make sure of that, the IRS requires that IRA owners withdraw a portion of their account each year after a certain age with a Required Minimum Distribution (RMD). For a diligent saver who spent their career contributing to the account, this can create a significant tax headache. Without careful planning, the onset of RMDs can force retirees to generate more income than they would otherwise need for their desired retirement lifestyle. The effects of this “RMD timebomb” can have a major impact on one’s tax situation, potentially increasing healthcare costs, taxes on Social Security benefits, and triggering additional taxes like the 3.8% Net Investment Income Tax.
A Real life RMD Tax Scenario
Paul (75) and Marie (73) are married, and each have IRAs—Paul’s at $1 million and Marie’s at $2 million. They both receive $25,000 in Social Security yearly. Their combined RMD in 2025 will be $115,000 ($40,000 for Paul and $75,000 for Marie), making their total income $165,000. But they usually only spend $120,000 a year. This means they are forced to pay taxes on $45,000 they don’t need, creating a frustrating tax issue. How could Paul and Marie have avoided this?
For those still working and saving, shifting a portion of contributions from Pre-Tax to Roth is a surefire way to reduce the impact of future RMD’s. Roth contributions do not reduce your current income, but withdrawals after age 59 ½ are tax-free. For this reason, Roth IRAs are not subject to RMDs during the lifetime of the account owner. While Roth contributions are a certain way to avoid the RMD timebomb, they are not necessarily best for everyone. For example, a high-income saver may decide to continue making Pre-Tax contributions to their company retirement plan if they expect to be in a lower tax bracket in retirement. As with any financial decision, there is no one-size-fits all solution.
RMD Tax Planning
For retirees who have not reached RMD age, proactive tax planning can make all the difference. In Paul & Marie’s case, if at age 66 they had a taxable income of $90,000, they would be in the 12% tax bracket. If they knew their tax rate would jump to at least 24% once RMDs began, they may consider extra IRA withdrawals to reduce their dollars subject to future RMDs. With the right planning, they could smooth out their tax rate throughout retirement, placing themselves in the 22% tax bracket each year instead of facing a sudden jump in the RMD years. The goal of efficient tax planning is not always “how can I reduce my current year taxes” but rather “how can I reduce my lifetime total tax paid.” When it comes to RMD tax planning for retirees, the tradeoff is often taking a kick to the shin today in lieu of a knockout punch down the road.
At Pathfinder Wealth Consulting, our advisors are attentive to the unique tax situations of our clients. We consider the current and future tax implications of our client’s financial decisions, and proactively communicate with clients and their tax professionals about strategies that benefit their big-picture financial plan. If you are concerned about the tax impacts of RMDs or seek tax-conscious financial planning, give us a call at (910) 793-0616 and we will be happy to talk with you about how we can help.
Pathfinder Wealth Consulting does not offer tax advice. You should consult a tax professional regarding your individual situation.
This is a hypothetical example and is for illustrative purposes only. No specific investments were used in this example. Actual results will vary. Past performance does not guarantee future results.
Advisory services offered through Commonwealth Financial Network®, a Registered Investment Advisor.

Wilmington Health Facility Sells For $9.4M
Cierra Noffke
-
Oct 26, 2026
|
While downtown also benefits from general fund expenditures, the municipal service district (MSD) “is a way of having some additional money...
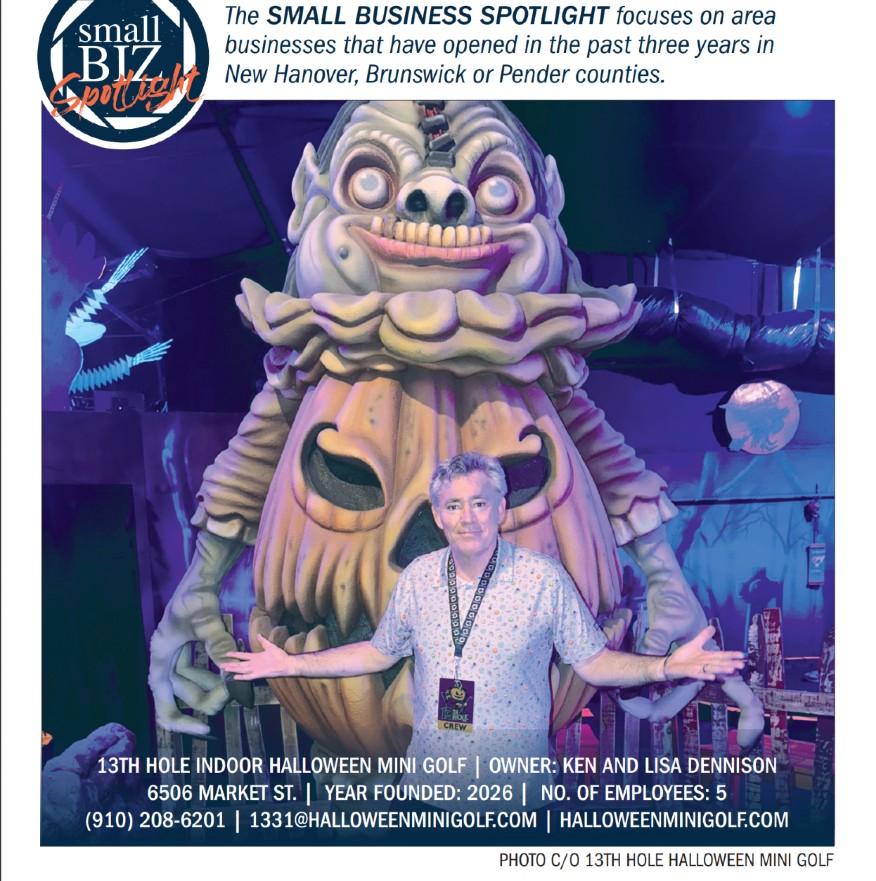
“Our vision is to create a mini-golf experience that becomes a welcoming space for everyone who enjoys a fun adventure with friends and fami...
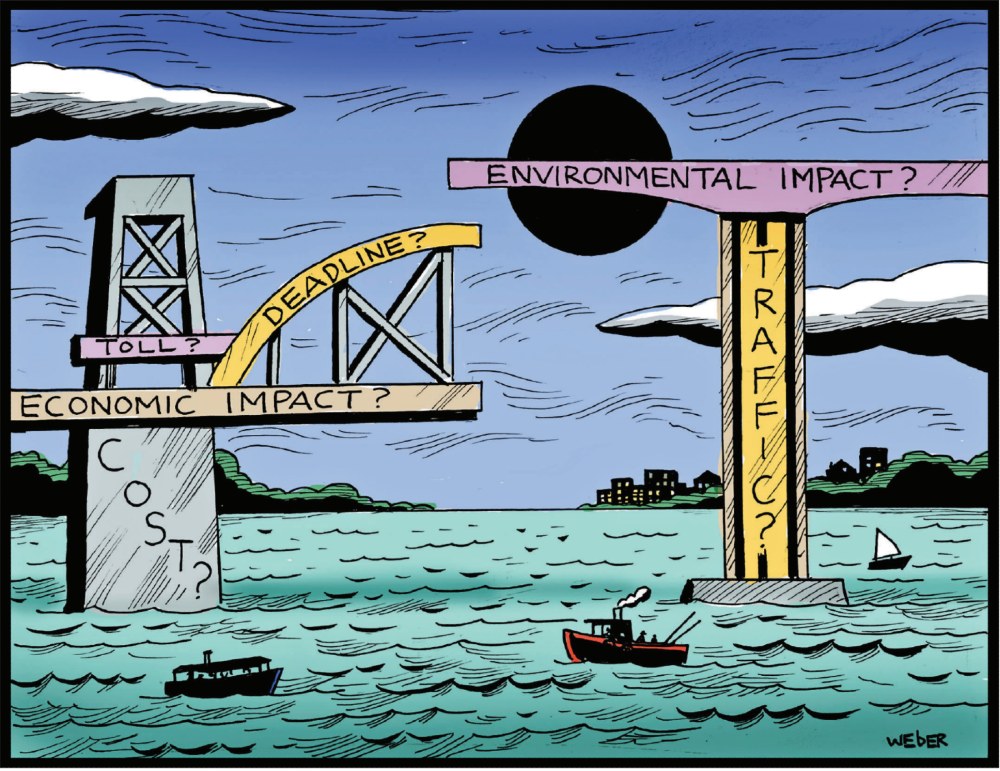
Support for the lower, movable-span bridge dominated spoken comments at the public hearings, and city officials have thrown their support be...
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.