One of the biggest areas of concern for buyers of real estate is losing out on their earnest money deposit.
If something goes awry in this transaction and it turns out that my loan application doesn’t get approved, how can I be sure I’ll get my deposit back?
Since many of my friends and colleagues are Realtors, I am often asked if there is anything I can do as a mortgage broker to help ensure that the earnest money deposits made by their buyers are protected. One of the best strategies for protecting a buyer from losing his or her deposit is to simply add a loan contingency.
When a contingency is added to the paperwork associated with the loan, it allows the buyer to avoid losing their earnest money deposit if something happens and the deal doesn’t get approved within 21 days of acceptance of the offer. Once the contingency is removed, the buyer has to either complete the deal or forfeit the earnest money deposit, as it is with any purchase transaction.
Considering most earnest money deposits are a minimum of around $1,000 and they can go up to three percent of the purchase price or higher, based on the buyer’s preference, it’s easy to see why someone could have a bit of anxiety about losing out on it if the deal falls through.
The additional paperwork and regulations imposed on lenders as a result of the financial crises only strengthens the point in regards to the advantage of adding a loan contingency. An average loan file now contains approximately 500 pages. If the lender accurately checks every box, crosses every ‘T’ and dots every ‘i’ on 499 pages but misses one, then the loan will not get approved until the issue is corrected.
This could potentially cause the deal to fall apart and the buyer to forfeit his or her earnest money deposit.
Additionally, there are numerous other speed bumps that could derail a transaction, even after everything starts to look good and it seems like the loan will be approved:
Patrick Stoy (NMLS Numbers 39527 and 39166) has 16 years of mortgage lending experience. Patrick is CEO of Wilmington-based Market Consulting Mortgage, which he started in 2005 with a mission to build lifelong customer relationships by providing real value. To learn more about Marketing Consulting Mortgage, visit www.macmtg.com. Patrick can be reached at [email protected] or 910-509-7105.


Ashworth Joins Mincey Bell Rhoades Law Firm
Staff Reports
-
Sep 15, 2026
|
|
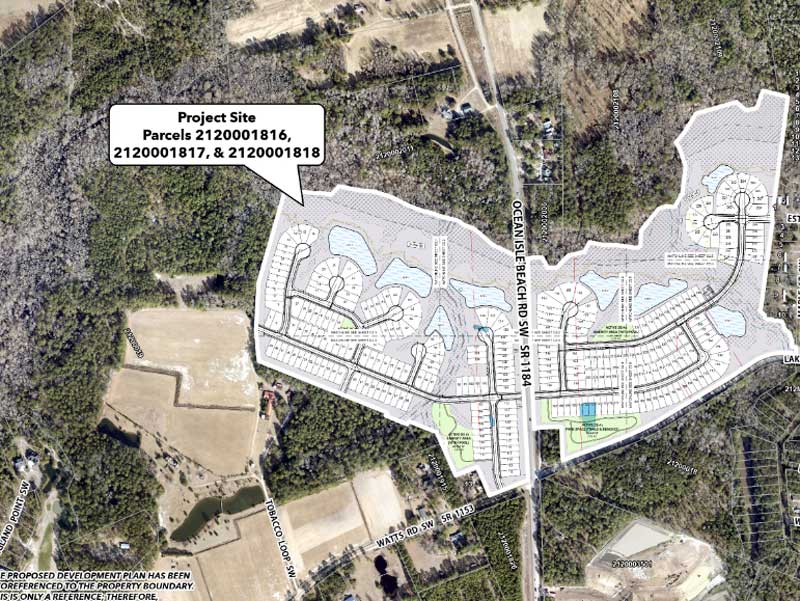
Brunswick County Planning Board To Consider 450-home Development Plans
Cierra Noffke
-
Sep 14, 2026
|
|
Pipe And Valve Distributor Opens Wilmington Branch
Staff Reports
-
Sep 15, 2026
|
|
Wilmington-area Companies Named Finalists For NC Tech Awards
Cierra Noffke
-
Sep 15, 2026
|
|
Southport-Oak Island Chamber Announces Summer Awards
Staff Reports
-
Sep 15, 2026
|
|
At $1 million and above, buyers have more choices than they did during the pandemic-era market, and they have more time to make decisions, a...
Glass, specifically optical fiber, has become integral to the expansion of the internet and AI infrastructure. And Corning Inc., a leading g...
Funded by donations, offerings and grants, Hope Recovery is permanently housed in the former Devon Park United Methodist Church and hosts mo...
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.