For the majority of this year, those of us with interests in real estate have been operating underneath the ominous, confusion-casting shadow known as the TILA-RESPA Integrated Disclosures (TRID). These new disclosures have been surrounded by misinformation and Chicken Little-style hysteria about added costs and potential delays in closing times.
A result of the Dodd-Frank Wall Street Reform and Consumer Protection Act, TRID was designed to protect the consumer. To achieve that goal, the Consumer Financial Protection Bureau inserted a number of waiting periods into TRID to ensure that consumers have ample time to thoroughly review any changes to their transactions.
It would be an true statement to say that everyone in the industry, especially mortgage brokers and real estate agents, experienced at least a little anxiety about the impact of TRID. Even Ken Trepeta, director of real estate services of the government affairs branch for the National Association of Realtors, commented that mortgage brokers, Realtors, buyers and sellers should “expect a one to two week delay in closings” because of TRID.
As a result of all this trepidation, many Realtor- and mortgage-broker associations banned together and successfully lobbied for a delayed implementation of the rules to ensure that everyone would have adequate time to prepare.
The final implementation of TRID went into effect on October 3, and I’m happy to report that the buyers I have been working with did not experience a delay in their closing times. The sky didn’t fall. Overall, I have to say that TRID has exerted a positive impact on the industry.
Before October 3, lenders were required to provide borrowers with four different disclosure forms, which contained overlapping, inconsistent language. With the integration of these disclosures, the process has been streamlined and there is less paperwork involved.
One of the largest benefits that TRID has provided for the consumer is that the law now requires lenders to give borrowers a closing disclosure statement three business days before the settlement of their transaction, when before it was only one business day. This has stemmed the tide of procrastination in the industry and provided added protection for borrowers.
An additional waiting period of three business days applies when certain changes to a loan are made, such as:


YMCA Dives Into Project Bringing Olympic-sized Swimming Lanes To Market Street
Cece Nunn
-
Nov 16, 2026
|
|
Institutional Investors Enter Local Industrial Market In Recent Deals
Emma Dill
-
Nov 16, 2026
|
This category honors an executive whose job performance is considered exemplary by people within their organizations, peers and community me...
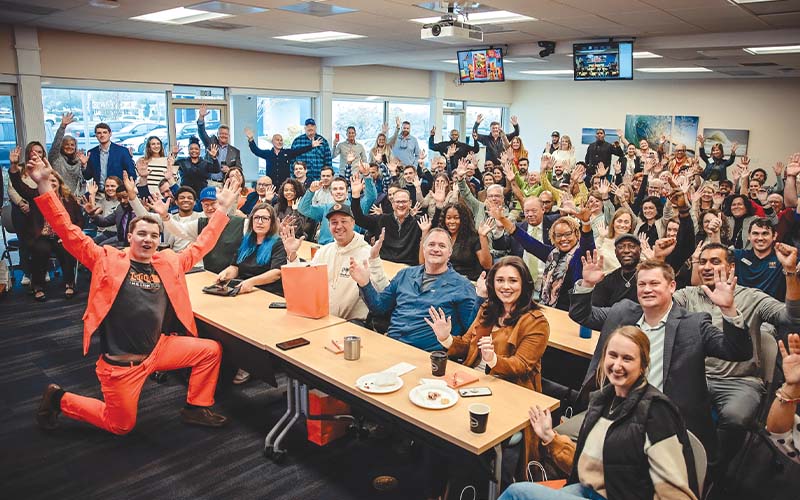
The program has reached more than 100 cities nationwide. Wilmington’s chapter consistently draws a crowd, and its organizers say momentum ha...
This category honors a physician whose performance is considered exemplary....
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.