This article is really geared toward a very specific group of homeowners — those who know they are going to move to another home between one and two years from now and have never considered renting their home instead of selling it. But even if you’re not planning to move in the next one to two years, you might in the future, so this article may benefit you too.
For most homeowners, the mortgage on their homes is their largest overall debt, and the monthly mortgage payment is the largest of their monthly expenses. For many, a large mortgage payment is the number one obstacle that keeps them from growing their net worth and finally “getting ahead” financially. It is often assumed that giving up a large chunk of hard-earned work income to pay a fat mortgage payment each month is just a fact of life that is never going away. A mortgage is typically perceived as a big, ugly debt that hovers overhead like a black cloud, refusing to allow the light of prosperity to shine through. When it’s time to move, it is also often assumed that the only reasonable course of action is to sell the current home to afford the mortgage for the new home.
However, with a shift of perception and a willingness to think outside the box, one might see that a mortgage is really just a loan that contains hidden value. I’m talking about an opportunity to transform one’s current home into a source of monthly revenue that will not only cover the mortgage on the new home, but also generate a profit. I’m talking about becoming a landlord and renting one home to pay for another, and then some.
I know. I know. The very word “landlord” turns people off, and that’s unfortunate because in most cases, the upside of being a landlord far outweighs the downside. Renting property is actually much simpler than people think. It’s also one of the fastest and most reliable ways to make money because real estate has the best guard against inflation. With very few anomalous exceptions, over time rent always goes up. Think of renting your previous home as keeping a valuable asset and having someone else pay for it. In essence, they are building your wealth for you.
If you’re planning to move and interested in renting your current home instead of selling it, here are some things to consider:
The best mortgage choices for a homeowner, and the smartest way of leveraging the value hidden in a loan, is unique for each person and dependent on multiple factors, including: age, family size, current financial status, future intentions and goals. The opportunity to build wealth by renting your property to others, as described here, may not be the smartest choice for some homeowners. However, I would encourage every homeowner to at least consider the possibility of renting and meet with a lending advisor with the expertise to ask the right questions and determine if renting your home is a good wealth-building option for you.
Patrick Stoy has 15 years of mortgage lending experience. Patrick is CEO of Wilmington-based Market Consulting Mortgage, which he started in 2005 with a mission to build lifelong customer relationships by providing real value. To learn more about Marketing Consulting Mortgage, visit www.macmtg.com. Patrick can be reached at [email protected] or 910-509-7105.


Ashworth Joins Mincey Bell Rhoades Law Firm
Staff Reports
-
Sep 15, 2026
|
|
Brunswick County Planning Board To Consider 450-home Development Plans
Cierra Noffke
-
Sep 14, 2026
|
|
Pipe And Valve Distributor Opens Wilmington Branch
Staff Reports
-
Sep 15, 2026
|
|
Wilmington-area Companies Named Finalists For NC Tech Awards
Cierra Noffke
-
Sep 15, 2026
|
|
Southport-Oak Island Chamber Announces Summer Awards
Staff Reports
-
Sep 15, 2026
|
|
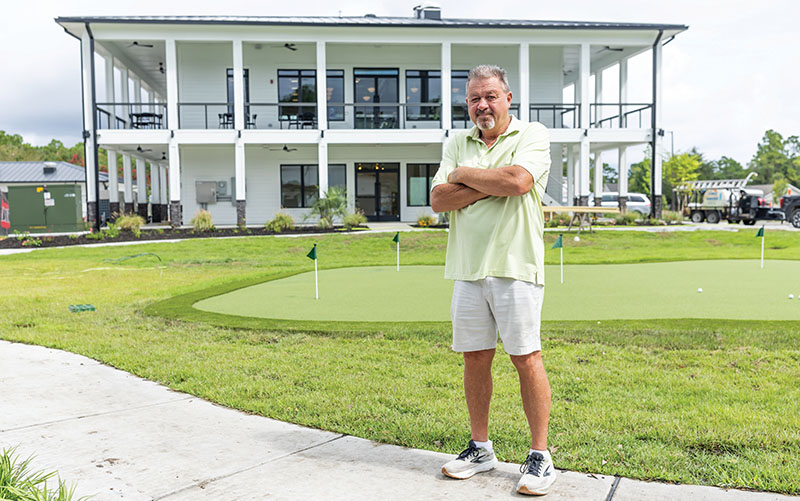
One of the clubs in Wilmington has 11 indoor pickleball courts, four covered, lighted outdoor courts, two new clay tennis courts, an outdoor...
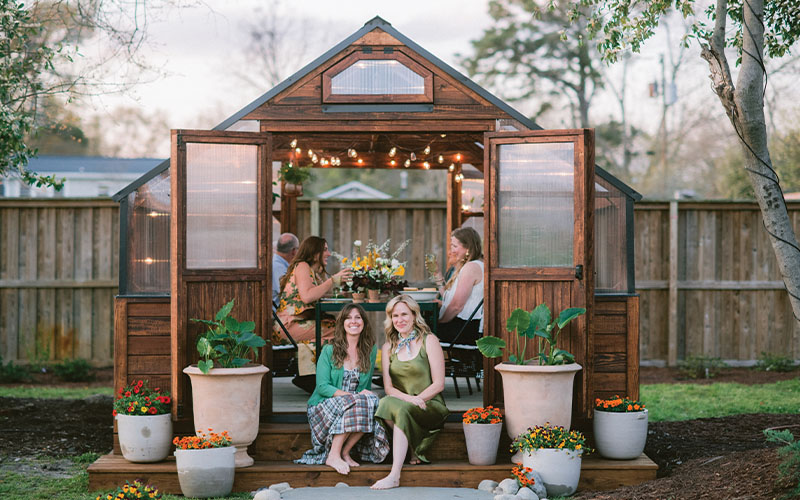
The expanding footprints of Perennial Harbor and Blossom Bay are among the latest examples of growth in the Soda Pop District, which stretch...
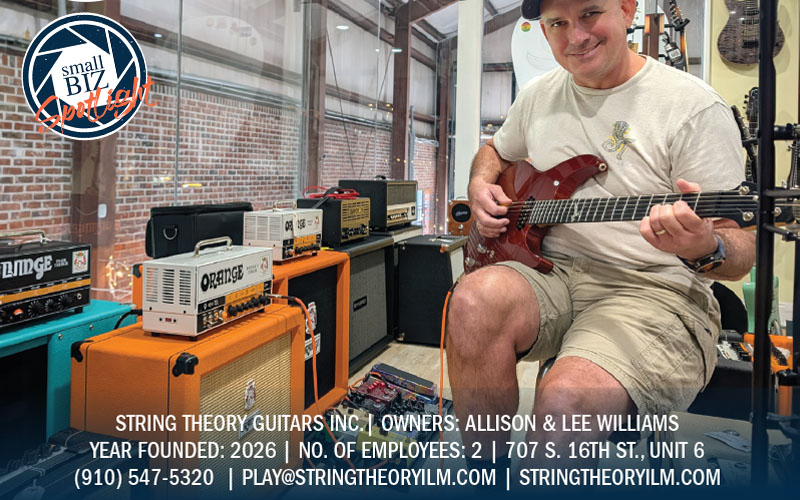
"We love Wilmington and the live music scene here, and we wanted a way to be a part of the music community without having to start work at 9...
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.